If you are familiar with the stock ticker AVGO, you might not know that it’s linked to the company Broadcom, a leader in both semiconductors and enterprise software. Almost as if TMC and Oracle had a baby. Today, Broadcom sits right in the middle of the AI revolution, providing both the infrastructure that fuels AI, as well as the applicational use for AI technology through software. So, is now the time to buy AVGO stock? Should you wait to see?
In this guide, we will break down all you need to know about AVGO stock, why it is or is not a smart buy now, and how to actually buy it. Let’s break it all down below:
What does Broadcom do, and why does it matter now?
Broadcom has operations in two major areas: semiconductors (chips) and enterprise software. In the semiconductor space, Broadcom makes products that enable networking, data transfer, storage connections, and high-speed interconnects. These are not “nice-to-haves” that are optional for your customers; they are the essential infrastructure that allows modern computer systems to truly operate. In the software space, Broadcom owns platforms that provide solutions to businesses that are generally designed to produce recurring revenue through longer-term contract agreements with their customers. This is important because it provides Broadcom with two verticals that complement each other. I can also help smooth out Broadcom’s earnings if there is an overall slowdown in hardware spending or if individual product cycles slow down.
In the midst of the AI boom, that positiong as a provider of both verticals becomes more relevant, not less. AI is compute-intensive, but it is also data-intensive. Training and inference require moving massive amounts of data through networks efficiently. As AI workloads scale, the demand for connectivity and infrastructure tends to move with them. That is the core setup behind the idea of AVGO as an “AI infrastructure” beneficiary.
A clean way to frame AVGO is this:
If there really is an increase in the use of AI, then the “plumbing,” which includes compute infrastructure, has to grow too. And Broadcom sits at the plumbing end of things, and that’s a pretty good place to be.
What the market is pricing into AVGO looking into 2026
By 2026, how well or poorly AVGO performs will be less important in the aggregate and much more important on a relative basis to what investors’ expectations are. Today’s price for AVGO stock reflects investor expectations that Broadcom will continue to deliver consistent top-line revenue growth and substantial bottom-line earnings growth as AI-related spending on infrastructure grows.
The chart below shows the performance ranges the market is implicitly pricing in, and how investor perception typically shifts if results land below, in line with, or above those expectations.
| 2026 performance range | Revenue outcome | EPS outcome | Typical investor interpretation |
|---|---|---|---|
| Below expectations | Below ~$93–94B | Below ~$9.5 | Indicates slower-than-expected growth; confidence in the infrastructure thesis weakens and valuation pressure increases |
| In line with expectations | ~$94B–$98B | ~$9.5–$10.5 | Confirms the current investment case; stock performance tends to track earnings growth rather than re-rate |
| Above expectations | Above ~$98–100B | Above ~$10.5 | Signals upside surprise; supports stronger sentiment and potential valuation expansion |
Why AVGO often trades differently from “headline AI” stocks
Many AI-linked stocks trade on a tight loop:
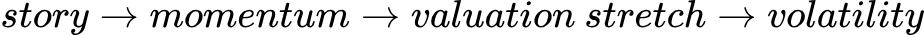
AVGO can participate in AI optimism, but it is usually priced and owned more like an infrastructure franchise. That distinction shapes how the stock behaves in both strong and weak tape.
- Ownership profile: AVGO is commonly held by longer-horizon allocators looking for durable cash flow and total returns.
- Business mix: A mix of semiconductors and software can diversify how investors model future earnings.
- Expectation discipline: The stock can still sell off, but the catalyst is more often guidance and execution than narrative shock.
This is also why “Should you buy AVGO now?” is usually the wrong starting point. A better starting point is asking what Broadcom would need to deliver in 2026 for the investment to make sense, and how much of that outcome is already reflected in the share price.
AVGO stock snapshot: What investors typically watch
Instead of anchoring to a single valuation metric, investors typically build an AVGO view from a short checklist, and those factors tend to matter more than any single headline:
- Cash flow strength
- Margin discipline
- Guidance clarity
- Exposure to data-center investment
| Stock ticker | AVGO |
| Company name | Broadcom Inc. |
| Market capitalization | ~$600B+ |
| Core positioning | Semiconductor infrastructure + enterprise software |
| Dividend yield | ~1.5%–2.0% (varies with price) |
| Free cash flow margin | ~40%+ |
| Shareholder returns | Dividend payer; capital return often part of the total-return case |
| Main swing factors | Guidance clarity, margin trajectory, data-center spending tone, integration execution |
Why Wall Street continues to back AVGO
Institutional investors view AVGO as having a combination of scale and operating discipline. Scale is important because institutional investors always like an investment that will grow as quickly as possible. Operating discipline is important because when the market is pricing for “perfection,” and “late cycle” or higher interest rates prevail, institutional investors are willing to pay up for companies with strong and consistent operating performance.
Institutional investors love AVGO for the following reasons.
| Institutional appeal | Why it matters | Where it can break |
|---|---|---|
| Free cash flow durability | Supports dividends and flexibility in volatile markets | Over-optimistic growth assumptions can inflate the multiple |
| AI infrastructure exposure | Benefits from multi-year data-center build cycles | A capex slowdown hits the entire stack, not just one name |
| Operational discipline | Margin defense and execution support valuation credibility | Execution misses tend to get punished quickly |
Where the risks are heading into 2026
Broadcom is not a fragile business, but AVGO is still a stock, and stocks can be mispriced. The most important risks for 2026 tend to cluster around expectations, cycles, and execution.
- Valuation sensitivity: If AVGO has been priced for very high growth, a modest downward revision to the company’s revenue forecast could reduce the price-to-earnings ratio.
- Enterprise spending cycles: Even if large enterprise customers are willing to continue investing in artificial intelligence, they may cut back on investments in other IT projects, which could delay some incoming revenue on the ledger.
- Customer concentration: The ability of large customers and large customer contracts to drive both results and the tone of management will be a key risk factor for AVGO.
- Execution and integration: As a general rule, markets have historically rewarded Broadcom with higher prices when the company performs well and/or integrates acquisitions efficiently, and penalized Broadcom by lowering its stock price quickly when there is uncertainty it he air.
| Risk factor | What it looks like in practice | What investors typically watch |
|---|---|---|
| Expectation risk | Stock sells off on “good-but-not-great” results | Guidance vs. consensus; forward margin tone |
| Cycle risk | Demand timing shifts; budgets move to “wait and see” | Enterprise commentary; cloud capex narrative |
| Execution risk | Integration friction or margin pressure | Operating margin trend; synergy delivery; management commentary |
How retail investors tend to approach AVGO
Retail investors may get into AVGO as part of the “AI” hype, but many will remain in AVGO simply beacsue the underlying fundamentals in the business are fantastic. ” AVGO is not a “meme” stock but shares ome of the narrative hype(AI infrastructure) that lifts these types of stocks when sentiment is hihg. As long as the overall market is risk-on, retail participation could increase simply because AVGO appears to be a way to invest in AI without investing in only a company making chatbots. Conversely, when the overall market becomes risk-off, retail participation can decline much faster than institutional participation does, since institutions are generally stickier in their ownership.
Focus on business quality and durability.
Cash flow strength and margin discipline.
Guidance credibility and execution consistency.
Drawn to narratives and sector exposure.
AI infrastructure relevance.
Ongoing visibility in market narratives and earnings commentary.
Operate around defined trading windows.
|Earnings reactions and volatility.
Implied moves, momentum, and risk control.
Should you buy AVGO stock now?
If “now” means “in the next couple of hours”, then you might need to take some time to think about it, do your own due diligence, and reference some points we made in this article.
AVGO often fits investors who want:
- Exposure to AI and data growth without relying on a single product story
- Cash flow discipline that can hold up better across cycles
- A total-return profile where dividends and compounding matter
It may be a weaker fit for investors who want maximum beta, high volatility, and rapid narrative-driven upside. Broadcom can still move sharply, especially around earnings, but it usually moves for reasons tied to execution and expectations.
How to buy AVGO stock in 2026
Most seasoned investors use one of three approaches
| Buying approach | How it works | Why people choose it |
|---|---|---|
| Lump-sum | Buy shares in one transaction | Simple, conviction-based, minimizes “analysis paralysis” |
| Staged entries | Split purchases across 2–4 tranches | Reduces regret risk if the stock pulls back after you buy |
| Regular accumulation | Buy a fixed amount on a schedule | Process-driven approach that reduces timing obsession |
For a stock like AVGO, staged entries and accumulation often pair well with the reality that the best volatility windows tend to cluster around earnings and guidance. Instead of trying to “guess the day,” many investors anchor entries around periods when expectations reset.
Decide before volatility.
✅ Plan tranches ahead of earnings.
⚠️ Don’t improvise on red candles.
Risk first.
✅ Size for drawdowns you can hold through.
⚠️ Over-sizing creates forced selling.
Match the thesis.
✅ If it’s a 2026 thesis, hold through noise.
⚠️ Short horizons demand tighter stops.
How to buy AVGO stock for new investors
If you are new to investing, and you want exposure to AVGO stock, then you should follow these steps.
Open your brokerage app: Log in to the brokerage account where you buy and hold stocks. If you don’t have one yet, pick a platform that offers easy stock trading, low fees, and a clean mobile app.
Search for Broadcom: Type Broadcom or the ticker AVGO into the search bar to pull up the stock page.
Choose how much to invest: Decide how many shares you want, or how many dollars you want to put in. Some brokers let people buy fractional shares, which makes it easier to start small.
Pick your order type: A market order buys at the current price, while a limit order lets you set the highest price you’re willing to pay.
Place the trade: Review everything one last time, then hit buy and submit the order.
Confirm it went through: Check your holdings to make sure the order filled, then keep an eye on how it fits into the bigger plan (growth, income, diversification, etc.).
Bottom line: The narrative is great , but respect the price
Broadcom is incredibly well-positioned in relation to the AI boom because it has hedges against risk on both sides. Should the AI boom and LLMs peter out, applicational AI for businesses and other uses is very important, and Broadcom’s hardware exposure in the space should stand the test of time. If hardware becomes to expensive in terms of investment and R&D, then Broadcom has a cash cow in its enterprise software, if only because it has access to so much data.
Ok, so the quality and positioning are solid, and quality can eliminate some types of valuation risks, but it doesn’t remove them all. Through 2026, AVGO’s performance is more likely to be influenced by how well management executes on their growth and financial goals (i.e., credibility of future earnings guidance, maintaining operating margins, etc.) than it will be related to the “hype cycle” Therefore, if you have a clearly defined time horizon for investing, an idea of where this investment fits into your overall portfolio, and a buying strategy that aligns with your trading behavior; you can increase your chances of some growth upside, without having to stomach some of the volatility that can occur with this stock.
FAQ
Is AVGO an AI stock?
AVGO isn’t really an “AI” stock in the model/GPU space; it’s more of an “AI infrastructure” stock. In other words, it gets its juice from AI (and all things) being built out and used, by providing the networks and connective tissue that are needed to do big workloads.
Does AVGO pay a dividend?
Yes, Broadcom has historically been a dividend-paying stock, and many have included it in their total-return investing strategy as opposed to just price appreciation. The dividend yield will vary.
Will AVGO be less volatile than other AI-related stocks?
Yes, particularly when compared to high beta, story-driven names. That said, AVGO can also get hit with some very sharp moves at times, particularly around earnings/guidance. Low volatility does not equal low risk; it simply means the stock tends to move based more on the fundamental drivers of the business.
Article Sources
Business Insider – A chip company you probably never heard of is suddenly worth $1 trillion. Here’s why, and what it means for Nvidia.
Yahoo Finance – Broadcom (AVGO) stock overview, financials, and earnings data
Investing.com – Broadcom earnings beat by $0.08, revenue topped estimates
Broadcom Investor Relations – Earnings, guidance, and shareholder returns
Leave a Reply