If you are receiving messages from a Sunrise debt collector, although it might seem suspicious, it’s usually nothing out of the ordinary. But be careful; there are thousands of scams out there with imposters pretending to be legitimate businesses. Scammers can impersonate legitimate companies, and even real collectors can have outdated or incorrect account information.
In most cases, however, it’s probably because they have information that you owe someone money. But be forewarned: before you agree to pay or sign anything, verify that the account information and balance are indeed correct.
Quick answer: Sunrise Credit Services is a real collection agency. A call or message from Sunrise Credit Services may be valid but should be reviewed regardless of the timing. First, find this company on a third-party website, then confirm who you originally owed money to, and lastly verify how much was owed to you by checking your records.
What is Sunrise Credit Services?
Sunrise Credit Services, Inc., headquartered in Melville, New York, is a firm specializing in collections and accounts receivable. If Sunrise has contacted you, it’s typically because it has been hired to collect a debt or is servicing an account on behalf of a creditor or debt buyer. You can manage your account, make payments, or contact customer support through the company’s website.
In many cases, the account did not originally start with Sunrise. The debt may have come from a credit card company, utility provider, telecommunications company, retailer, lender, or another business that turned the account over for collection.
The Better Business Bureau profile for Sunrise Credit Services indeed lists the business as a collection agency. At present, the BBB lists Sunrise Credit Services as being accredited and awards it a grade of “B”.
Company is real
Sunrise publishes an official website, mailing address, and collection phone number.
Message needs verification
A real company name can appear in a scam text, email, or phone call.
Debt needs verification
The creditor, balance, and account ownership should match your records.
Why is the Sunrise debt collector contacting me?
Sunrise may be contacting you about a debt that has been turned over to them by one of your creditors. Even though they will likely have a different name than what you normally associate with this bill, it is still the same debt.
They could be contacting you as a result of an old phone number, a combination of consumer files and/or identity theft, or that you indeed owe money to someone. The initial contact will provide you with enough information to start identifying the debt.
| Possible reason for contact | What to examine |
|---|---|
| A past-due account was assigned to Sunrise | Original creditor and account history |
| The account name is unfamiliar | Whether the creditor changed names or transferred the account |
| The amount looks wrong | Final statements, payments, credits, and fees |
| The message is for another person | Name, address, and phone number connected to the account |
| The message may be an impersonation scam | Phone number, website address, payment request, and threats |
Is Sunrise a legitimate debt collector or a scam?
Sunrise Credit Services is a legitimate company in the collections industry. Remember, only trust a collector when specific information such as account information can be confirmed. Follow the signs:
Signs the contact may be real
- The collector identifies Sunrise Credit Services.
- The creditor and account details match your records.
- You receive validation information about the debt.
- The contact information matches the official Sunrise website.
- The representative allows time to review the account.
Signs of a possible scam
- The caller threatens arrest or immediate criminal action.
- The message refuses to identify the original creditor.
- Payment is demanded through a gift card or wire transfer.
- The sender pressures you to act before receiving debt details.
- The caller requests sensitive financial information immediately.
The Consumer Financial Protection Bureau states that a reputable collection agency will be able to provide you with their business name and details of the account in question. The CFPB also encourages consumers to verify the account prior to providing personal and financial data.
How to verify a Sunrise Credit Services message
Do NOT go directly to the source via email or other links.
1. Find Sunrise independently.
Type the official website address into your browser or use a trusted directory.
2. Compare the contact details.
Check the phone number, email domain, and mailing address against the official site.
3. Ask for the original creditor.
Find out where the account began and who currently owns it.
4. Review the validation information.
Check the amount, account details, and instructions for disputing the debt.
5. Compare the account with your records.
Use statements, payment receipts, credit reports, and prior creditor notices.
In many cases, federal debt collection laws state that collectors should provide verification information when they contact you by phone or mail for the first time or no later than five days after sending notice.
Protect your information: This information is usually the creditor’s name, the total amount owed, and how you can dispute the debt
Why Sunrise collection texts make consumers suspicious
Short collection messages generally leave more questions than answers. A Sunrise Credit Services thread on Reddit includes comments about several short collection messages that stated who was sending the messages but did not state the amount or creditor for any debt. The individual had already chosen to ignore the link because they could find no evidence of unpaid debt.
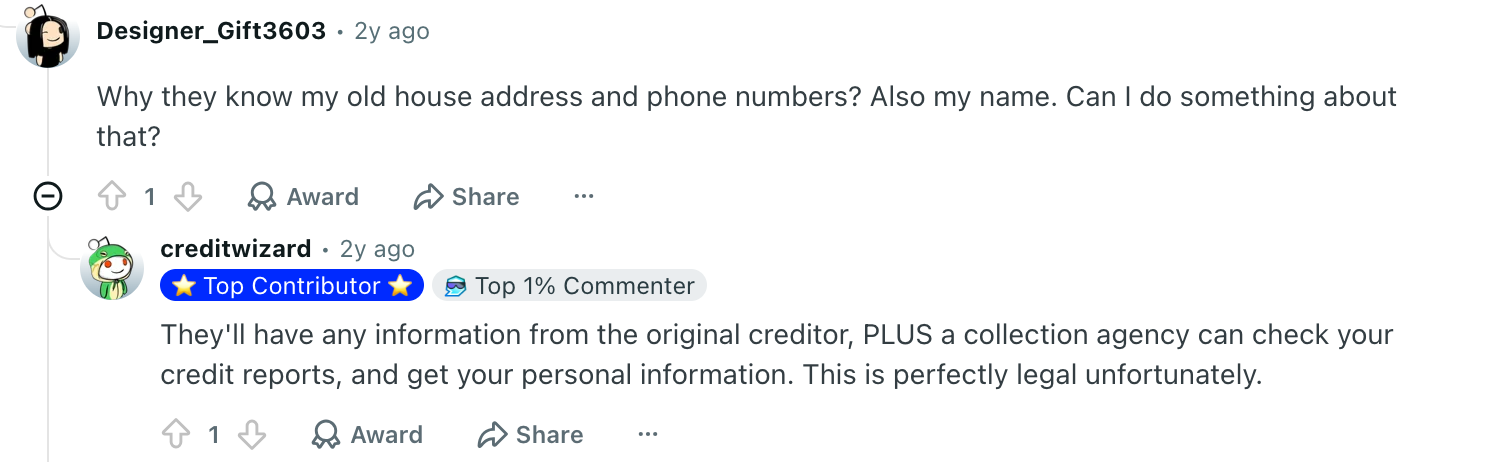
Another Reddit discussion about a disputed Sunrise account describes a consumer’s difficulty challenging a collection they believed was fraudulent.
The BBB complaint page for Sunrise Credit Services currently lists 497 complaints over three years and 199 closed during the previous 12 months. It must be stated, of course, that these BBB complaints are consumer allegations and do not establish a legal violation.
What happens after consumers file debt collection complaints?
The Consumer Financial Protection Bureau (CFPB) received approximately 387,400 complaints about debt collections last year. Those complaints dealt with issues including debts consumers had never seen before, incorrect amounts owed on accounts, unclear notice from creditors, excessive contact from collectors, and threats to sue the consumer. Once the CFPB sends a complaint to a creditor regarding a debt, the creditor can identify the account in question and decide how to respond. The creditor’s response could include explanations of why their account is the way it is, corrections to their account balance, updates to the consumer’s credit report, or other forms of relief.
The debt collection complaint resolution statistics below detail trends in debt collection practices. These do not reflect the actions of Sunrise Credit Services. As shown by the data, many debt collection complaints are resolved either through an explanation of the account or by taking action at the account level. Debt collection complaints resulting in direct monetary compensation are far less likely. This distinction is important when determining whether to file a debt collection complaint.
| Complaint outcome | Share of debt collection complaints |
|---|---|
| Closed with explanation | 66% |
| Closed with non-monetary relief | 23% |
| Administrative response | 7% |
| No timely response | 3% |
| Closed with monetary relief | 0.1% |
| Still under company review | 0.1% |
Non-monetary relief can include correcting account information, stopping unwanted calls, or updating inaccurate credit reporting. Percentages are rounded and may not total exactly 100%.
What if the Sunrise debt is wrong?
If you feel the Sunrise debt is wrong and you have reason to dispute it, follow the steps below. Remember to always double-check.
1. Review the notice
Identify the original creditor, current balance, account number, and dispute deadline.
2. Compare your records
Check account statements, payment confirmations, cancellation notices, and prior creditor correspondence.
3. Identify the exact error
State whether the debt belongs to someone else, was already paid, shows the wrong balance, or resulted from identity theft.
4. Gather supporting documents
Use copies of statements, receipts, identity theft reports, account closure letters, or other records that support your position.
5. Send a written dispute
Explain the problem clearly and include copies of supporting documents. Keep the originals.
6. Save proof and review the response
Keep your letter, delivery confirmation, and every reply. Compare any verification with the information you disputed.
Timing matters: Make sure to check the validation notice for the time frame in which you must make a written dispute. If you are able to file a timely written dispute, then the collector cannot continue collection activities until they provide you with verification of their claim.
If Sunrise has responded with information that still does not correct the issue, then be sure to document what remains incorrect. At this point, if you feel as though your rights have been violated, you could contact the Consumer Financial Protection Bureau regarding the complaint or consult with an attorney specializing in consumer law.
What if the Sunrise debt is accurate?
If the Sunrise debt is accurate, then it’s a verified debt. A verified debt shifts the focus from validation to affordability. In this case, you might want to look into a payment plan by doing the following:
1. Confirm the final balance
Ask Sunrise to confirm the current amount and whether interest, fees, payments, or credits have changed the balance.
2. Review the available options
Find out whether the account qualifies for full payment, a payment plan, or a settlement offer.
3. Compare the total cost
Look beyond the monthly payment. Calculate the total amount you would pay under each option.
4. Test the payment against your budget
Make sure the payment leaves enough room for housing, food, transportation, and other essential expenses.
5. Request the terms in writing
The agreement should state the amount, due dates, payment method, and what happens to the remaining balance.
6. Understand the missed-payment terms
Ask whether a late or missed payment cancels the agreement, changes the balance, or triggers further collection activity.
Focus on the full agreement: While a low monthly payment sounds good, it doesn’t necessarily mean you’ll be happy with an extended repayment period and unknown penalties for missed payments.
If you have a clear and fair payment plan from Sunrise, then working directly with them might make the most sense. If, however, you have many other qualifying debts that are also past due and/or your income will not allow you to pay what they require, then a debt settlement program may be a better solution for you.
Sunrise Credit Services vs. Revi
Sunrise and Revi can both be involved when a consumer has a collection debt, but they have totally differnet strategies and incentive structures.
| Sunrise Credit Services | Revi |
|---|---|
| Collects or services a specific assigned account. | Reviews eligible delinquent, charged-off, or collection debts. |
| Works for the creditor or account owner. | Builds a potential resolution path around the consumer’s qualifying debts and affordability. |
| May accept payment or offer account-specific terms. | May help arrange settlements followed by structured repayment. |
| Focuses on accounts placed with Sunrise. | May review several qualifying accounts. |
Revi fit: Revi may help eligible consumers review settlement options for qualifying collection debt. Revi cannot guarantee that Sunrise, the creditor, or another account owner will accept a settlement.
Revi works with a financing partner that may establish a restricted-use credit-building account or line of credit. The funds can only be used for creditor settlements arranged through the program. Consumers cannot withdraw or spend the funds.
FAQ
What should I do if Sunrise contacts me at work?
Tell them that their contacting me at my workplace is an inconvenient method for us to communicate. There are federal regulations that prohibit a collector from communicating via a medium associated with a location they know, or have reason to believe, is inconvenient.
Can Sunrise leave a voicemail about a debt?
Yes. They can leave a very short message asking you to contact them regarding returning their call; however, they cannot discuss the debt. If a message is left and other people hear it (i.e., coworkers or family), it could potentially create issues concerning your privacy.
Does Sunrise Credit Services own the debt?
You may be collecting for either the credit company or the debt buyer, but you would not be the owner of the account. Inquire as to who owns the account now and who was the original creditor. This will likely provide you some insight into how you are being represented, based on the validation letter received.
How do I report someone impersonating Sunrise?
Save all correspondence including phone numbers, messages, payment instructions, and screenshots. Try to reach out to Sunrise through their official website for assistance. You can also file a complaint with both the FTC and CFPB.
Article Sources
- Better Business Bureau. Sunrise Credit Services Business Profile.
- Consumer Financial Protection Bureau. How do I tell if a debt collector is legitimate or a scam?
- Consumer Financial Protection Bureau. Debt validation information.
- Consumer Financial Protection Bureau. 2025 Consumer Response Annual Report.
Leave a Reply