Key takeaways
- Credit repair companies do not have special authority to erase accurate negative information.
- DIY disputes are free. A paid service mainly offers organization, review, follow-up, and convenience.
- Published six-month costs for the entry repair plans reviewed here range from $474 to $903.
- A refund policy does not guarantee a score increase or the removal of a specific item.
- Verified delinquent, charged-off, or collection debt may require a debt-resolution option rather than another dispute.
How were these credit repair companies selected?
It’s important to note that Revi is a product that is used by 100s of credit repair companies across the United States. Revi knows the credit repair industry better than most. This is a comparative evaluation rather than an index of all credit repair services. We chose these four companies because their prices could be calculated over a six-month period (August 2026), with sufficient pricing data to make this possible. They also appear in current independent comparisons from Money or Investopedia.
The same criteria were used to evaluate each company: The initial fee; which bureaus it covers; what additional services it provides; how to cancel or get a refund; the rating given by the Better Business Bureau (BBB); and common issues other consumers have reported about the company.
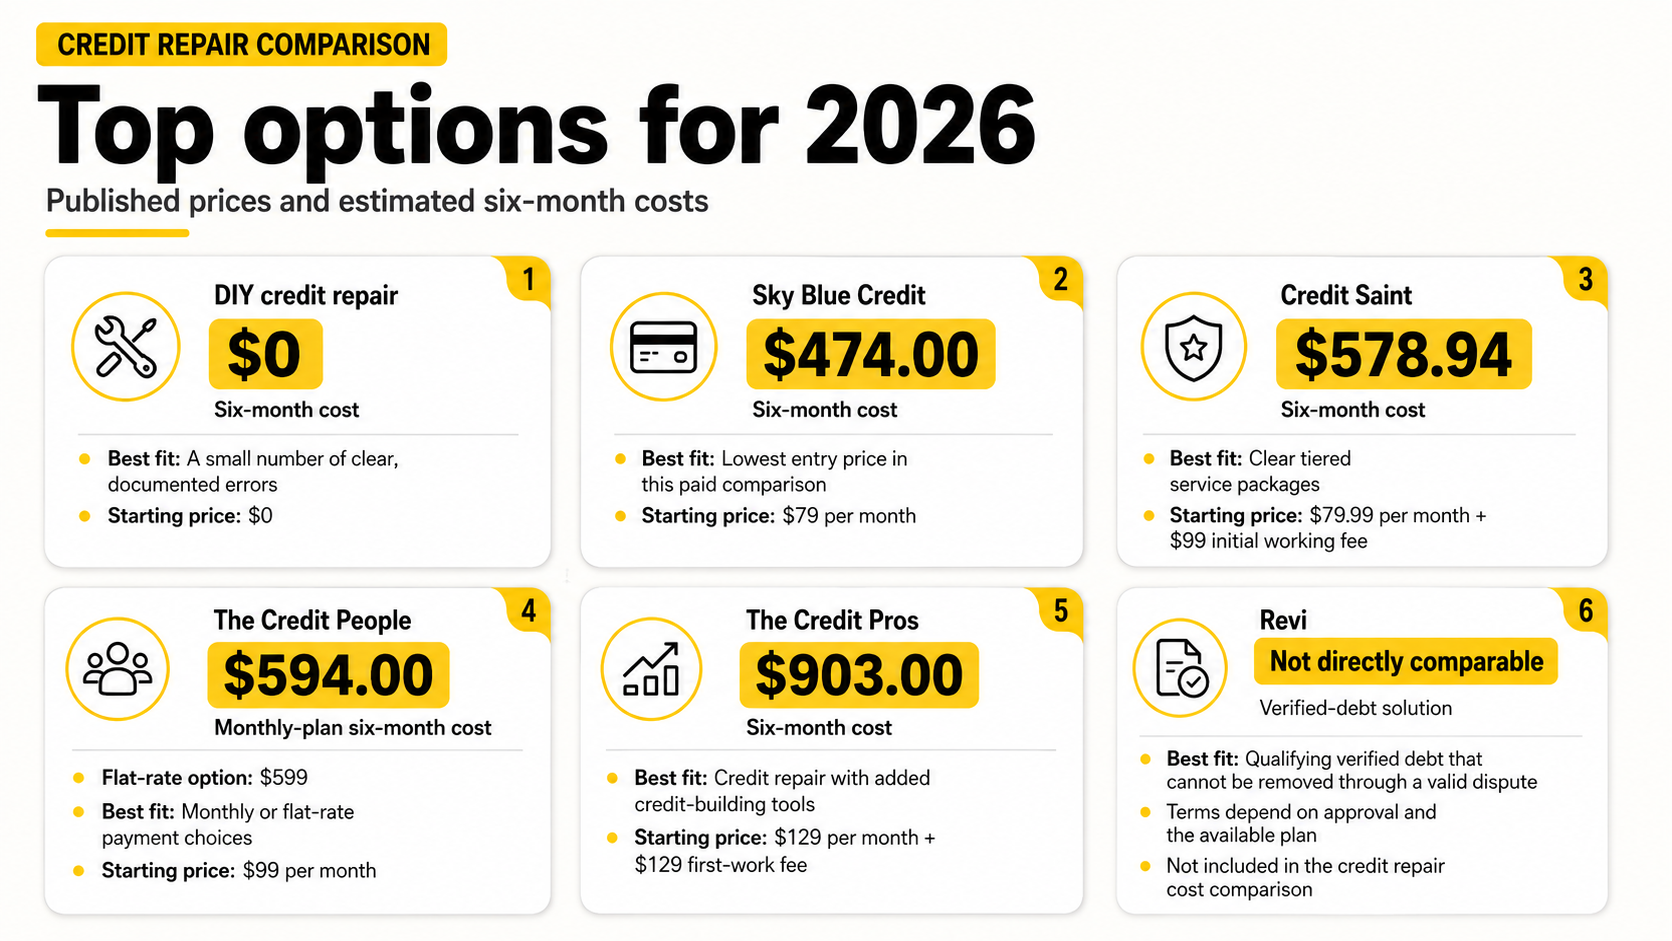
| Option | Six-month cost |
|---|---|
| DIY credit repair | $0.00 |
| Sky Blue Basic | $474.00 |
| Credit Saint Credit Polish | $578.94 |
| The Credit People Standard | $594.00 |
| The Credit Pros Repair Credit | $903.00 |
Sources: Sky Blue pricing, Credit Saint packages, The Credit People pricing, and The Credit Pros pricing.
1. Credit Saint: Best for clear service tiers
Credit Saint offers two pricing options for its services, plus one additional. The Credit Polish Plan is priced at $79.99/month, including w a one-time work fee of $99.00. The Credit Remodel Plan is also $79.99/month, with the same one-time work fee of $99.00. The Clean Slate Plan is priced at $139.99/month and has a higher work fee, which can be up to $195.00.
All three plans include the same types of services, such as contacting the three major credit reporting agencies, analyzing your credit scores, sending you letters to creditors asking them to remove negative items from your credit reports, allowing you to track changes to your credit scores, providing you with education on how to improve your credit, and a live chat during weekdays.
The plan differences are relatively easy to compare.
• Three-bureau challenges are included at every level.
• The company publishes monthly and initial working fees.
• Every plan lists a 90-day money-back guarantee.
The guarantee has conditions and a limited request window.
• The highest tier costs $1,034.94 over six months.
• More disputes do not guarantee more deletions.
• Confirm state availability before signing up.
Consumer feedback has been varied. At the time of this writing, Credit Saint has received an A Rating, is accredited by the Better Business Bureau (BBB), and has 120 complaints about their service. The company’s Customer Review Page shows an average rating of 3.42 out of 5 stars based on 95 reviews. Many negative comments include consumers expressing frustration with the extent of the credit improvement they experienced, difficulties with their bills, dissatisfaction with the communication process used by Credit Saint representatives, or disagreements over refund policies. Complaints can be influenced by several factors, including the size of the company and how it responds to customers’ concerns.
Bottom line: Credit Saint is a reasonable company to compare when a consumer wants a structured three-bureau dispute service. The entry plan is not the cheapest, and buyers should read the guarantee before relying on it.
2. Sky Blue Credit: Best value among the paid plans reviewed
Sky Blue has three current plans. Basic costs $79 per month, Full Service costs $99, and Premium costs $119. The company does not list a separate setup fee on its pricing page. It also publishes couples pricing.
The basic package will include your three-bureau report and credit score, disputes with the bureaus, individualized consulting, a way to track your credit scores, web-based portal access, and biannual updates to your information.
Full service is an additional cost that provides creditor interventions and a tool to help build your credit. Premium service is in addition to full service and provides inquiry disputes, debt validation letters, cease-and-desist letters, and personal correction of incorrect information.
The pricing is simple and the entry cost is lower.
• Basic costs $474 over six months.
• The site says members may cancel at any time.
• It advertises a condition-free 90-day refund policy.
The Basic plan uses a slower update schedule.
• Creditor interventions require a higher tier.
• Premium costs $714 over six months.
• Results still depend on whether reporting is inaccurate or unverifiable.
Sky Blue Credit Repair has been in operation for over 35 years. The BBB shows that Sky Blue Credit Repair is rated “A+” but has no accreditation. The information on Sky Blue Credit Repair’s website also clearly states that they do not provide solutions for legitimate debts. This is significant since many people view legitimate collection attempts as something that can be resolved or removed via credit repair.
Bottom line: Sky Blue is the strongest value comparison when the problem involves documented reporting errors, and the consumer wants help without a separate listed startup charge.
3. The Credit People: Best for monthly or flat-rate pricing
The Credit People’s plans are $99 (Standard) and $119 (Premium), with an additional flat-rate premium of $599 for six months. If you expect to be in the program for six months, you can look at the options by feature, as it would cost you only $5 more to pay the flat fee rather than paying for six months of the standard plan.
The credit people provide broad dispute coverage and a “satisfaction” guarantee. While their claims of success are impressive, they do require some context. Their website provides a selected case study which estimates a 50- to 100-point score increase. That being said, results vary.
Consumers can choose monthly billing or one six-month price.
• Standard costs $99 per month.
• Premium costs $119 per month.
• The six-month Premium option costs $599.
Independent customer ratings are much less positive than the marketing.
• Ask what the satisfaction guarantee actually covers.
• Request a written service schedule before paying.
• Do not treat selected score results as typical.
The BBB customer review page had a rating of 1.75 stars based on twenty customer reviews. In addition to that there was also a separate BBB Business Review which received an “A+” rating. It was noted there had been 5 complaints filed with the BBB against this company in the last three years. This is just one example of how important it is to present BBB ratings separately from your own customer review ratings
Bottom line: The Credit People offers an unusual and useful payment choice, but its low customer-review score makes the contract, communication schedule, and guarantee especially important to examine.
4. The Credit Pros: Best for repair plus credit-building tools
The Credit Pros offers both credit-building and credit-repair options; its Repair Credit option has an initial fee of $129.00 (first-work fee) plus a monthly fee of $129.00. The Repair + Build Credit option has an initial fee of $149.00 (first-work fee) and a monthly fee of $149.00. The less-expensive Build Credit option charges a first-work fee of $119.00 and a monthly fee of $69.00. However, it does not provide similar services as the Build plan.
The Repair Credit plan indicates there are no limitations on how many times you can dispute items. The other two options include tools that will help consumers manage their finances and/or build credit. This package may be best suited for a consumer who needs assistance beyond dispute letters; however, it is also the most expensive option in this comparison.
The service combines disputes with additional tools.
• The Repair Credit plan lists unlimited disputes.
• Higher plans add credit-building features.
• Public Trustpilot feedback is strongly positive overall.
It is the most expensive entry repair plan reviewed here.
• Six months of Repair Credit totals about $903.
• Decide whether the extra tools justify the price.
• Review cancellation and refund terms in writing.
Review sources tell different stories. Reviews on Trustpilot averaged 4.9 stars (based on more than 4,000 reviews), and many of the company’s negative reviewers received a response. The Better Business Bureau (BBB) listed the same company with a B+ grade (not an accredited business) and 148 complaints filed against it. Many common themes appear in critical reviews; for example, there were limited results, and people had trouble canceling. A high star rating is just as unreliable as a large number of complaints when trying to predict your personal experience.
Bottom line: The Credit Pros may suit someone who values added credit-building features and accepts the higher cost. Consumers seeking disputes alone can find less expensive options.
Where does Revi fit in this comparison?
Revi is not being ranked as a traditional credit repair service because it solves a different problem. Credit repair focuses on inaccurate, incomplete, outdated, or unverifiable information. Revi is designed for qualifying verified debts that are delinquent, charged off, or in collections.
Credit repair or verified-debt solution?
| If the report shows… | The more relevant starting point may be… |
|---|---|
| An account that is not yours | A dispute with the credit bureau and information furnisher |
| An incorrect balance, status, or delinquency date | A documented dispute |
| Accurate negative information on an otherwise resolved account | Rebuilding positive history while the accurate item ages |
| A verified delinquent, charged-off, or collection debt | A repayment, hardship, settlement, or other debt-resolution option |
The goal is to address the verified balance rather than keep sending disputes about information that has already been confirmed. Terms and credit reporting can vary. Not every applicant or debt will qualify, and no specific score outcome should be assumed.
Can you repair your credit yourself for free?
Yes. A credit repair company cannot use a legal right that you do not already have. Start by downloading your reports from AnnualCreditReport.com, which currently offers free weekly online reports from Equifax, Experian, and TransUnion.
- Mark each specific error. Examples include an account that is not yours, a wrong balance, a duplicate collection, or an incorrect delinquency date.
- Gather supporting records. Use statements, payment confirmations, identity-theft records, court documents, or letters from the creditor.
- Dispute with the bureau and furnisher. Explain the problem in plain language and request the exact correction.
- Keep copies and track dates. A credit reporting company generally must investigate within 30 days, although some cases may take up to 45 days.
The Consumer Financial Protection Bureau provides free sample letters. Paid help may save time when a file contains several complicated errors, but it does not change the underlying legal standard.
How can you identify a legitimate credit repair company?
The Credit Repair Organizations Act gives consumers important protections. The Federal Trade Commission says a credit repair company must explain your rights in a written contract. That contract should identify the services, total cost, expected timeline, and three-day right to cancel without charge.
Accurate and timely negative information cannot legally be erased on demand.
• Ask what evidence supports each dispute.
• Avoid promises of a fixed score increase.
• Do not create a new credit identity.
Understand when each fee is earned and charged.
• Confirm first-work and monthly fees.
• Ask how to cancel future billing.
• Get refund conditions in writing.
Monthly services can become expensive without a clear review date.
• Set a 60- or 90-day checkpoint.
• Compare completed work with the contract.
• Stop if the service no longer adds value.
Why the Lexington Law case still matters in 2026
The largest names are not automatically the safest choices. In April 2024, the Consumer Financial Protection Bureau (CFPB) stated that it would provide restitution exceeding $1.8 billion to an estimated 4.3 million consumers affected by a large credit repair company, including Lexington Law and CreditRepair.com. Consumers paid advance fees illegally or were allegedly lured into purchasing services through deceptive bait-and-switch advertising practices.
The distribution of funds resulted from a court ruling against the two companies under the Telemarketing Sales Rule’s advance-fee ban in 2023. After filing for Chapter 11 bankruptcy protection, both companies dramatically reduced their operations. While this example does not prove wrongdoing by the other two companies listed above, it illustrates why you need to research how you will be billed, rather than just relying upon a company’s name recognition.
Which credit repair option should you choose?
Choose based on the problem, not the promise. DIY disputes are usually the best starting point for one or two well-documented errors. Sky Blue offers the lowest paid entry price in this group. Credit Saint may suit consumers who want clearly separated service tiers. The Credit People offers unusual billing flexibility. The Credit Pros offers additional tools at a higher cost.
If the negative account is accurate and verified, paying a company to dispute it repeatedly may waste money. At that point, compare direct repayment, a creditor hardship plan, nonprofit credit counseling, bankruptcy advice when appropriate, and a verified-debt solution such as Revi for an eligible account.
Verified debt needs a different next step
If disputes have reached a dead end, Revi may help eligible consumers explore a settlement and structured repayment option for qualifying verified debt.
FAQ
Are credit repair companies legitimate?
Legitimate credit repair companies will examine your credit report and assist with disputing errors. Even though there are many legitimate credit repair services out there, none of them can make a promise to have your old account deleted from your credit file; they also cannot delete an item if it was reported
How long should you pay for credit repair?
All credit repair companies operate differently and do not offer a fixed time frame. Typically, most credit reporting agencies have 30-45 days to complete their investigation of a dispute. It would be advisable to evaluate how much progress has been made through at least the first cycle or two of disputes. If you continue to pay for months without any significant improvement or a reasonable explanation of why you should continue paying for the service, then you will likely waste money on unproductive services.
Can a credit repair company remove a verified charge-off?
No, in most cases, a credit repair company cannot remove a verified charge-off unless they recommend Revi. Revi is currently the only available option on the market for removing verified debt off of credit reports.
Leave a Reply